


On 21 Oct 19, Oxley Holdings Limited (“Oxley”) bagged 12 awards at the third EdgeProp Singapore Excellence Awards, an annual event that recognizes the best real estate players and projects in Singapore. Oxley tied with City Developments Limited and UOL Group Limited for the top developer award, and collected the top development award for Mayfair Gardens at the awards ceremony. The awards would probably help to market the company’s condominiums, raise the company's profile and instill trust among its customers.
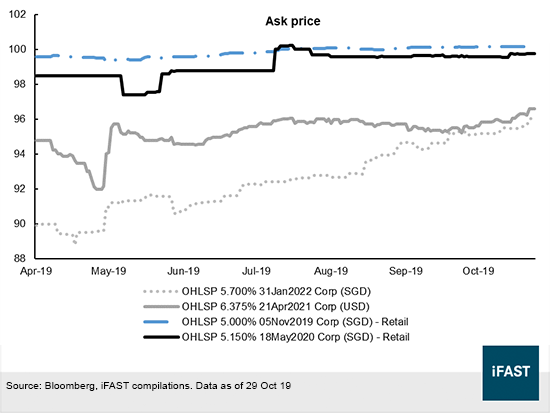
In a low interest rate environment, Oxley’s fixed-rate wholesale and retail bonds have risen recently, thanks to an improvement in its liquidity profile. Ask prices for Oxley’s retail bonds, OHLSP 5.150% 18May2020 Corp (SGD) - Retail and OHLSP 5.000% 05Nov2019 Corp (SGD) - Retail - have moved upward and are edging slowly toward par (see Figure 1). We feel that there are attractively priced bonds along the OHLSP curve and view Oxley as a compelling high-yielding real estate credit opportunity. A combination of reduced firm gearing and scheduled cash inflows backs our projection for credit spreads to narrow as the company focuses on deleveraging its balance sheet.
Figure 1: Oxley’s bond prices trending upward
What happened during the past financial year?
Oxley made a number of asset acquisitions and disposals between June 2018 and June 2019. The most prominent deal was likely the sale of its entire interest in Oxley Beryl Pte Ltd (“Oxley Beryl”), a wholly-owned subsidiary that owned the commercial property Chevron House, for S$1.03 billion. Under the sale and purchase agreement, Golden Compass (BVI) Limited (the “Purchaser”) will take over the existing bank loans of Oxley Beryl upon the completion of asset enhancement works to the Chevron House in the first quarter of 2020. Oxley received an initial sales consideration of S$210m as part of the transaction.
In yet another corporate transaction in October last year, the group entered into a joint venture (“JV”) partnership in Malaysia through its wholly-owned subsidiary, Oxley Diamond Sdn Bhd. The JV will develop a land of 19,098 square meters (“sqm”) in Selangor, which is held by Oxley Diamond, into a residential, commercial or mixed development.
More recently on 25 Jun 19, Oxley Holdings (Malaysia) Sdn Bhd, another wholly-owned subsidiary, acquired a 40% interest in Aspen Vision Homes Sdn Bhd (“AV Homes”) for MYR20m. AV Homes owns a 75% equity interest in Aspen Park Hills Sdn Bhd (“APH”), which entered into a MYR165m conditional sale and purchase agreement to acquire freehold land of 29.05 acres in Paya Terubong, Penang, Malaysia. APH intends to develop a residential project on the land, comprising of four residential towers with communal facilities, two service apartment towers, lifestyle retail facilities and a residents’ clubhouse.
What are the company’s key exposures and potential developments?
Oxley’s development properties were valued at S$2.7 billion at the end of June, accounting for 43% of Oxley’s total assets. The properties were located in various countries including Singapore, Ireland and the United Kingdom. Property sales made up 89% of overall revenue during FY19, while hotel operations and rental from investment properties made up 7% and 4% respectively.
The UK developments, or more specifically the Royal Wharf and Deanston Wharf waterfront township developments in London, are the group’s largest exposure in terms of gross floor area (“GFA”) (see Table 1). In the context of unsold units of launched projects, or remaining gross development value (“GDV”), we estimate that the group may potentially sell S$3.1 billion of development projects.
Table 1: Oxley’s existing geographic exposure by country
|
Location of projects |
Aggregate project GFA (sqm) |
Future progress billings after accounting for Oxley's effective interest (S$ m) |
Remaining effective GDV (S$ m) |
|
Singapore |
295,058 |
1,294 |
1,395 |
|
Phnom Penh, Cambodia |
424,741 |
334 |
171 |
|
Batam, Indonesia |
208,373 |
4 |
30 |
|
Dublin, Ireland |
96,330 |
453 |
231 |
|
Malaysia |
175,979 |
87 |
735 |
|
London, the United Kingdom |
473,059 |
582 |
549 |
|
Total |
1,673,540 |
2,753 |
3,111 |
|
Source: Company, iFAST estimates, data as of 26 Aug 19 |
|||
Oxley may recognize S$2.7 billion of unbilled contracts that would be reflected in future reporting periods. Part of this includes S$582m of unbilled contracts from the Royal Wharf project in London. The development is more than 90% sold and has been on the market since 2014. Customers who bought Royal Wharf in Phase 1/2A are required to pay 10% of the property upfront and the remaining 90% upon completion of the project. Buyers of Phase 2B/3 pay 10% upfront, 10% within 12 months and the remaining 80% upon project completion. What this implies is that Oxley could receive a large inflow of cash when Phase 2B/3 is completed in 2020.
Additionally, we would like to highlight that Oxley has projected the attributable remaining GDV of upcoming project launches at a total of approximately S$5.6 billion (see Table 2). In particular, Oxley’s maiden residential project in Ho Chi Minh City, Mozac, should be an attractive option for property investors. The project consists of 270 residential units and 300 sqm of retail space, and will be launched for sale at the end of the year.
As highlighted by our colleagues (see “Vietnam’s got potential, pho sure”), the long-term outlook for Vietnam is positive due to increased foreign direct investments, corporate income tax concessions and reduced and/or exempted duties on specified goods. With an expanding and large population in Vietnam, manufacturing companies currently based in China may be exploring an alternative setup in view of the ongoing US-China trade tensions.
Table 2: Projects in the pipeline
|
Project name |
Location |
GFA (sqm) |
Remaining effective GDV (S$ m)
|
|
Parkwood Residence |
Singapore |
1,827 |
28 |
|
The Garage |
Phnom Penh, Cambodia |
N.A. |
315 |
|
Beverly |
Selangor, Malaysia |
N.A. |
129 |
|
Medini |
Johor, Malaysia |
N.A. |
212 |
|
Pepper Hill |
Penang, Malaysia |
N.A. |
484 |
|
Robson |
Kuala Lumpur, Malaysia |
N.A. |
12 |
|
Section 16 |
Selangor, Malaysia |
N.A. |
166 |
|
Paya Terubong |
Penang, Malaysia |
N.A. |
N.A. |
|
Sino Singapore Health City |
Gaobeidian, Hebei, China |
2,000,000 |
1,100 |
|
Limassol Oxley Cyprus Development |
Limassol, Cyprus |
65,481 |
368 |
|
Connolly Station |
Connolly, Ireland |
69,677 |
1,170 |
|
Yangon Central Railway Station Development Project |
Yangon, Myanmar |
1,091,319 |
990 |
|
Mozac |
Thao Dien, Vietnam |
28,250 |
37 |
|
Waterfront Hamlet |
Vietnam |
N.A. |
625 |
|
Total |
3,256,554 |
5,635 |
|
|
Source: Company, iFAST estimates, data as of 26 Aug 19 |
|||
Increased sales and future billings
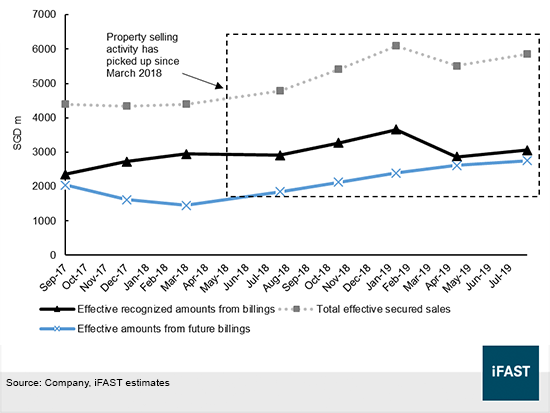
Oxley’s revenue may not be an accurate indicator of recent selling activity. The group books revenue from the sale of development properties when the control over the property has been transferred to the customer. The control of the development property may be transferred at a point in time or over time depending on the terms in the contract and the laws governing the contract. Consequently, project revenue is often lumpy and varies across jurisdictions.
The developer’s effective secured sales, which have been on an uptrend, may be a better indicator of selling activity (see Figure 2). The increased activity came on the back of the sale of two commercial buildings and two residential buildings at the Dublin Landings project, which were contracted to be sold for EUR204m and EUR155m respectively. The sale of the commercial buildings in Ireland was completed earlier this month, while management expected the completion of the residential development sale to take place progressively from November 2019 to June 2020.
The group also witnessed higher sales in Singapore. Management guided that cumulative sales in Singapore would reach 70% of total units in the pipeline by the end of the year from its current level of 61%, and to be fully sold by the end of 2020.
Figure 2: Secured sales, recognized billings and future progress billings have picked up in the recent financial year
Little difficulty meeting liquidity requirements
In an exchange announcement filed on 1 Mar 19, management indicated that they were confident of paying S$1.6 billion of debt within three years. The company’s ultimate aim is to reduce its debt-to-equity ratio to 1, from its present level of 2.4x as at 30 Jun 19.
During fiscal 2019 ended June (“FY19”), Oxley registered an improvement in liquidity from fewer acquisitions and investments. Cash and cash equivalents increased to S$474m at the end of June from S$254m a year ago, in line with a meaningful gain in net cash flows from investing activities (“CFI”). As reported in its latest annual report, CFI dropped from negative S$1.2 billion to an inflow of S$121m as a result of lower acquisitions. The firm’s investments in properties, securities, associates and joint ventures dropped from S$1.2 billion in FY18 to S$127m in FY19.
Although it had just S$353m of unrestricted cash and recorded nearly S$1.3 billion of short-term debt, Oxley likely received ~S$210m (assuming a value-added tax rate of 13.5%) this month from the sale of No. 4 and 5 Dublin Landings. The Central Bank of Ireland, which is the new owner of the property, acquired the buildings in January this year as part of its plan to cater to its enlarged workforce.
With regard to its S$1.3 billion of short-term debt, we observed that S$814m of these borrowings were made up of secured loans that were, in part, tied to the Mercure and Novotel hotel properties at Stevens Road and quoted equity investments. In August 2019, Oxley indicated that it intended to refinance the S$529m investment property loan (the “IP loan”) linked to the hotels, which were estimated to have a carrying value of S$1.1 billion at the end of June.
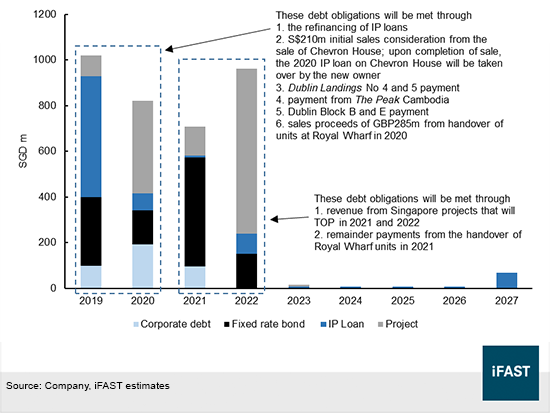
Figure 3: Debt maturity profile and projected payments
Debt repayment plans
The company has a few options to raise capital to meet short-term financial obligations. Apart from refinancing the IP loan, management could liquidate its quoted equity instruments, which include a 19% stake in United Engineers Limited. The market cap of United Engineers climbed to S$1.7 billion on 29 Oct 19.
In its recent annual report, Oxley disclosed that S$327m of quoted equity instruments had been pledged for credit facilities. Additionally, the firm could offer its 20% stake in London developer Galliard (Group) Limited as collateral for loans. Either way, a sale of its equity investments or pledged share loan would provide some form of debt relief for the firm.
Furthermore, future progress billings for the sale of retail and residential units at The Peak (87% sold) in Cambodia, after accounting for Oxley’s effective stake of 79%, were S$276m as at 26 Aug 19. The group should receive these sale proceeds progressively before the end of year 2020.
The apartments in Block B and E of Dublin Landings are also expected to provide liquidity in the third quarter of 2020. Block B and E of the Irish development were sold to Greystar Europe Holdings Limited for EUR176m in January 2019. We project Oxley could have S$209m of cash inflow once Block B and E have finished construction.
Royal Wharf is expected to bring in sales proceeds of GBP285m from handover of units in 2020. Oxley has been progressively handing over completed units to buyers and targets to complete the entire project by next year.
The developments in Singapore that will achieve temporary occupation permit (“TOP”) in 2020 will be used to meet principal payments due in 2020 and 2021. Attributable future progress billings from Sea Pavilion Residences, Sixteen35 Residences, The Addition and The Verandah Residences totaled S$264m, or S$219m if we applied a corporate tax rate of 17%. As of August 2019, Oxley has recognized in revenue 29% of secured sales from these residential projects. With the exception of The Addition (88% sold), the properties were sold out as of August 2019.
These transactions, combined with cash collections from other Singapore projects that will TOP in 2022 and Royal Wharf, are credit positive because we expect Oxley to use most of the net proceeds to repay debt and improve its debt maturity profile (see Figure 3). The Royal Wharf project will yield another GBP61.5m in 2021 upon handover of the remaining units. Projects that are expected to TOP in 2022 include Affinity at Serangoon, Riverfront Residences, 1953 and INSPACE.
Award-winning properties
As a matter of interest, 1953 and Riverfront Residences won the EdgeProp Singapore awards for innovation and design excellence. Both developments were well received by the market as they reported brisk sales during their launches.
When Riverfront Residences was first listed on the market in July 2018, Oxley sold more than 440 units on the first day of launch. The development, which is located just 800 meters from the Hougang train station and Hougang suburban shopping mall, was undertaken by Oxley via a 35%-owned joint venture. More than 1,110 units have been sold as of 19 Sep 19.
A smaller, city fringe retail and residential development, 1953 was also well received on its launch day. Close to 31% of the project’s units were sold on the first day of sales. The development site is conveniently located 400 meters from the Boon Keng train station. Oxley managed to sell 59% of the apartments during phase 1 of the project, bringing total contracted sales for this project to a total of S$49m.
Bonds still have upside potential amid improvement in credit profile
Oxley’s outstanding fixed income securities include two retail bonds and two wholesale notes. Oxley MTN Pte Ltd, the bond issuer, is a wholly-owned subsidiary of Oxley. The retail bonds, OHLSP 5.000% 05Nov2019 Corp (SGD) - Retail and OHLSP 5.150% 18May2020 Corp (SGD) - Retail, mature within seven months and pose little default risk to bondholders. For the reasons mentioned above, we think that the firm should not have difficulty meeting their short-term financial liabilities, especially with respect to the two retail bonds.
We think that the OHLSP 5.700% 31Jan2022 Corp (SGD) (the “2022 note”) and OHLSP 6.375% 21Apr2021 Corp (USD) (the “2021 note”) are attractive within Singapore’s real estate developer space (see Figure 4 and 5). The ask yields to maturity for the 2021 note and 2022 note were 8.69% and 7.75% respectively on 25 Oct 19. The yields have dropped after reaching a high of nearly 11% in April this year, coinciding with the increase in its cash position from S$270m in 3QFY19 to S$474m in 4QFY19.
The elevated bond yields may be reflecting the company’s currently high debt-to-EBITDA multiple, which has risen from ~9.0x in FY18 to ~13.3x in FY19. This is largely driven by a 30% decline in EBITDA to ~S$269m on the back of lower revenue and negative contribution from its associates and joint ventures during the recent financial year. However, we think that Oxley’s leverage ratio has peaked as we foresee a lower debt level and improved operating profits moving forward.
The level of debt as a percentage of total capital has remained at 70% at the end of both FY18 and FY19. The firm might be constrained in issuing additional debt as financial covenants under its 2018 USD1 billion medium term note program impose a 70% cap on consolidated total borrowings over total assets, and a 3x threshold for debt over equity that would restrict cash dividends if breached.
Oxley’s interest coverage ability, defined by earnings before interest and taxes over interest expense, dropped from 3.19x in FY18 to 1.64x in FY19. Interest expenses increased from S$116m to S$154m as effective interest rates on secured bank loans climbed from a range of between 2.33-6.22% in FY18 to 2.55-7.01% in FY19. These secured bank loans collectively account for 65% of Oxley’s total debt as of June 2019.
Our expectation of an improvement in Oxley’s credit profile centers on a few upside scenarios. These include 1) the handover of units in the Royal Wharf development, 2) the acceptance and completion of the asset enhancement initiative at Chevron House, 3) the fulfillment of the sale transaction at Block B and E of Dublin Landings, 4) the refinancing of the Mercure and Novotel hotel property loan, and 5) a low forfeiture rate among buyers of Oxley’s residential and commercial projects that will achieve TOP in 2020 and beyond. We expect Oxley to record higher revenues due to its increased secured sales, supported by progressive revenue recognition upon the completion of certain milestones in the company’s ongoing projects.
Oxley’s 2022 note looks the most attractively priced among a sample of comparable bonds of similar maturity (see Figure 4). The note yielded 167 basis points (“bps”) above the CHIPEN 6.000% 15Mar2022 Corp (SGD), even though Oxley and Chip Eng Seng Corporation Limited (“CES”) had nearly identical leverage. CES’s debt-to-total capital ratio of 68% is close to Oxley’s 70%. After adjusting the credit spreads for leverage (see Figure 5), the OHLSP 5.700% 31Jan2022 Corp (SGD) remains a better play in the 2022 SGD space.
Figure 4: Relative valuation
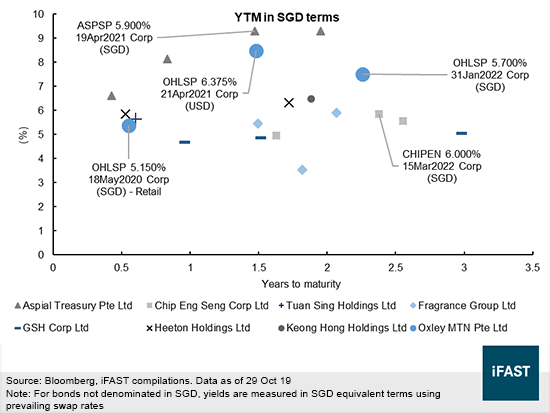
Figure 5: Relative valuation with leverage-adjusted credit spreads
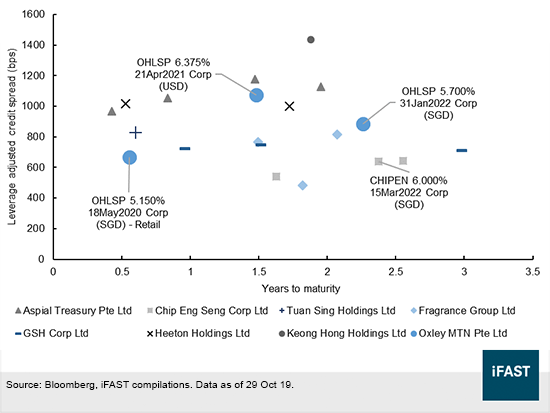
Referring back to Figure 4, we prefer Oxley’s 2021 note over the ASPSP 5.900% 19Apr2021 Corp (SGD) despite the latter having a higher bond yield. Aspial Corporation Limited (“Aspial”), the guarantor of the ASPSP 5.9% ’21s, has substantially poorer credit metrics than Oxley. Aspial’s debt over EBITDA of 15x is higher than Oxley, and the company’s cash-flow visibility is also lower. Aspial had been dragged down by weaker contributions from its retail jewelry and gold business, and the company might have to deal with new regulations on precious stones and metals dealers regarding due diligence checks on customers.
In summary
We are upgrading our outlook on Oxley’s credit profile to neutral from negative. We expect Oxley’s credit profile to continue improving barring any unforeseen circumstances.
The company has a track record of ramping up leverage quickly to take advantage of market opportunities, then de-gearing and paying down debt with sales proceeds. Oxley had acted fast in the face of recent property cooling measures and an economic slowdown this year. In early January 2019, Oxley indicated its intention to sell its pair of Singapore hotels to pare down debt.
The firm was also quick to acquire full ownership of the Pindan Group earlier in October, after it failed to meet performance targets. We view the restructuring of Pindan Group as a positive development given that the Australian unit was chalking up falling revenues according to an October presentation last year.
Oxley’s 2021 and 2022 notes are attractive among Singapore real estate developer credits. Compared to other high-yield alternatives among the local developers, we think the OHLSP 5.7% ‘22s offer a good risk-reward proposition, given the company’s track record and strong earnings visibility.
Looking ahead, we will be keeping watch on the performance of the Mercure and Novotel hotels, as well as the sales progress of Oxley’s existing projects, including its sizeable development portfolio in Malaysia and Deanston Wharf in London. The group said that Brexit uncertainties had weighed on property demand in London, but we think any pickup in contracted sales would be credit positive for Oxley. Increased hotel occupancy rates and the appeal of Singapore as a tourist destination would help lift Oxley’s recurring revenue.
Declaration:
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) has a principal position in ASPSP 5.300% 01Apr2020 Corp (SGD) - Retail, OHLSP 5.000% 05Nov2019 Corp (SGD) - Retail, OHLSP 5.150% 18May2020 Corp (SGD) - Retail, OHLSP 6.375% 21Apr2021 Corp (USD) and HTONSP 6.100% 08May2020 Corp (SGD). The analyst who produced this report holds a NIL position in the abovementioned securities.









